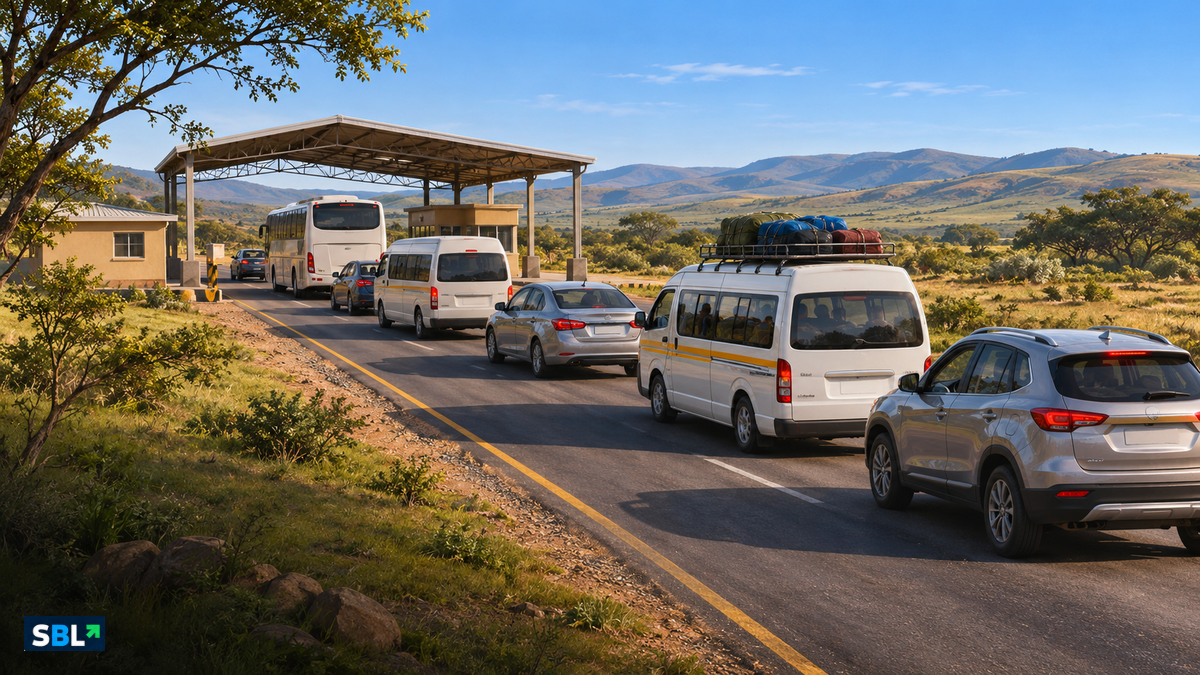
South Africa recorded 10.3% more international tourist arrivals in the first nine months of 2026 than a year earlier. But the increase is more concentrated than that national headline suggests: Mozambique and Lesotho supplied about 72% of the net gain, SBL calculations show.
That is useful information for tourism businesses planning for the summer. It points to the importance of neighbouring markets without establishing that every destination, hotel or tour operator is experiencing the same recovery.
Where the additional arrivals came from
Stats SA’s September tourism report, released on 28 October, records 8,416,835 tourist arrivals from January to September, against 7,634,261 in the same period of 2025. The difference is 782,574.
| Residence | Extra arrivals | Share of gain |
|---|---|---|
| Mozambique | 394,654 | 50.4% |
| Lesotho | 168,672 | 21.6% |
| All other markets, net | 219,248 | 28.0% |
| Total | 782,574 | 100.0% |
The two countries contributed 563,326 additional arrivals. Dividing that by the national increase gives 71.98%, rounded to 72%. This is their share of the increase, not their share of all arrivals or tourism spending. Their combined share of total arrivals was 37.3%.
September adds a caution
The same report shows September arrivals falling 1.3% year on year to 835,380. A positive nine-month result can therefore coexist with a weaker latest month.
In its 30 September statement on August, the Department of Tourism reported January-to-August growth of 11.7% and emphasised converting visitor demand into investment, jobs and wider economic opportunities. The subsequent nine-month rate is lower, although it remains positive. TimesLIVE’s 28 October reporting also records the 10.3% nine-month increase.
Neither comparison establishes what will happen over the festive season. The cumulative figure describes progress already recorded; September is one observation within that longer period.
SBL analysis: test the customer mix before expanding
The commercial lesson is to examine which source markets are generating demand. Stats SA reports nine-month growth of 12.5% for SADC-resident tourists and 3.8% for its overseas category. A business selling long-haul packages should therefore be cautious about treating the combined 10.3% as a forecast for its own customer base.
A useful planning check is to group confirmed bookings by customers’ residence and compare each group with the same period last year. That can distinguish broad-based growth from dependence on a few markets. It also avoids assuming that a national increase will reach a particular property or route. The exercise requires appropriate customer records; border counts cannot substitute for them.
Concentration also creates exposure. As an illustration, halving the two countries’ additional arrivals while leaving every other contribution unchanged would reduce the national net increase by 281,663, or 36%. This is an arithmetic sensitivity test, not a forecast or a claim that such a slowdown is likely.
The concentration finding is a reason to stress-test plans, not a prescription to abandon other markets. An operator could assess what happens to expected bookings if its largest source market weakens, while checking whether other markets can realistically fill the gap. No such forecast can be made for an individual business from this national release alone.
What the figures cannot settle
Stats SA counts border movements, not unique people, and flags missing data at some ports. A tourist is an overnight visitor, including someone staying in private accommodation. Country of residence is not necessarily the country travelled from.
Consequently, extra recorded arrivals cannot be translated directly into extra hotel customers, local jobs or rand revenue. SBL’s earlier accommodation-income analysis examines a separate measure and an earlier month. This analysis does not identify why individual markets changed, measure the effect of border-data gaps, or infer demand for any particular province.
Sources and calculations
The primary report supplies Annexure D’s country totals and Table 3’s September comparison. The Department of Tourism statement supplies the earlier eight-month context; TimesLIVE corroborates the reported national growth rate, rather than providing a separate count.
- National increase: 8,416,835 minus 7,634,261 = 782,574.
- Combined contribution: 394,654 plus 168,672 = 563,326; 563,326 divided by 782,574 × 100 = 71.98%.
- Combined share of arrivals: 3,138,017 divided by 8,416,835 × 100 = 37.28%.
- All comparisons use the published country-of-residence series. No missing values are estimated.
The September report lists 25 November as the expected date for the October release. The next useful test is whether monthly growth resumes and whether the cumulative gain becomes more widely distributed.
SBL Independent | Prepared and last checked: 4 November 2026.
Leave a Reply